ServicesMotor Truck Cargo Insurance
Motor Truck Cargo Insurance in Fairburn, GA
When a load is damaged, stolen or lost, the shipper looks to you. We set up motor truck cargo insurance around what you actually haul and what your broker contracts require, and we explain the exclusions before you sign.
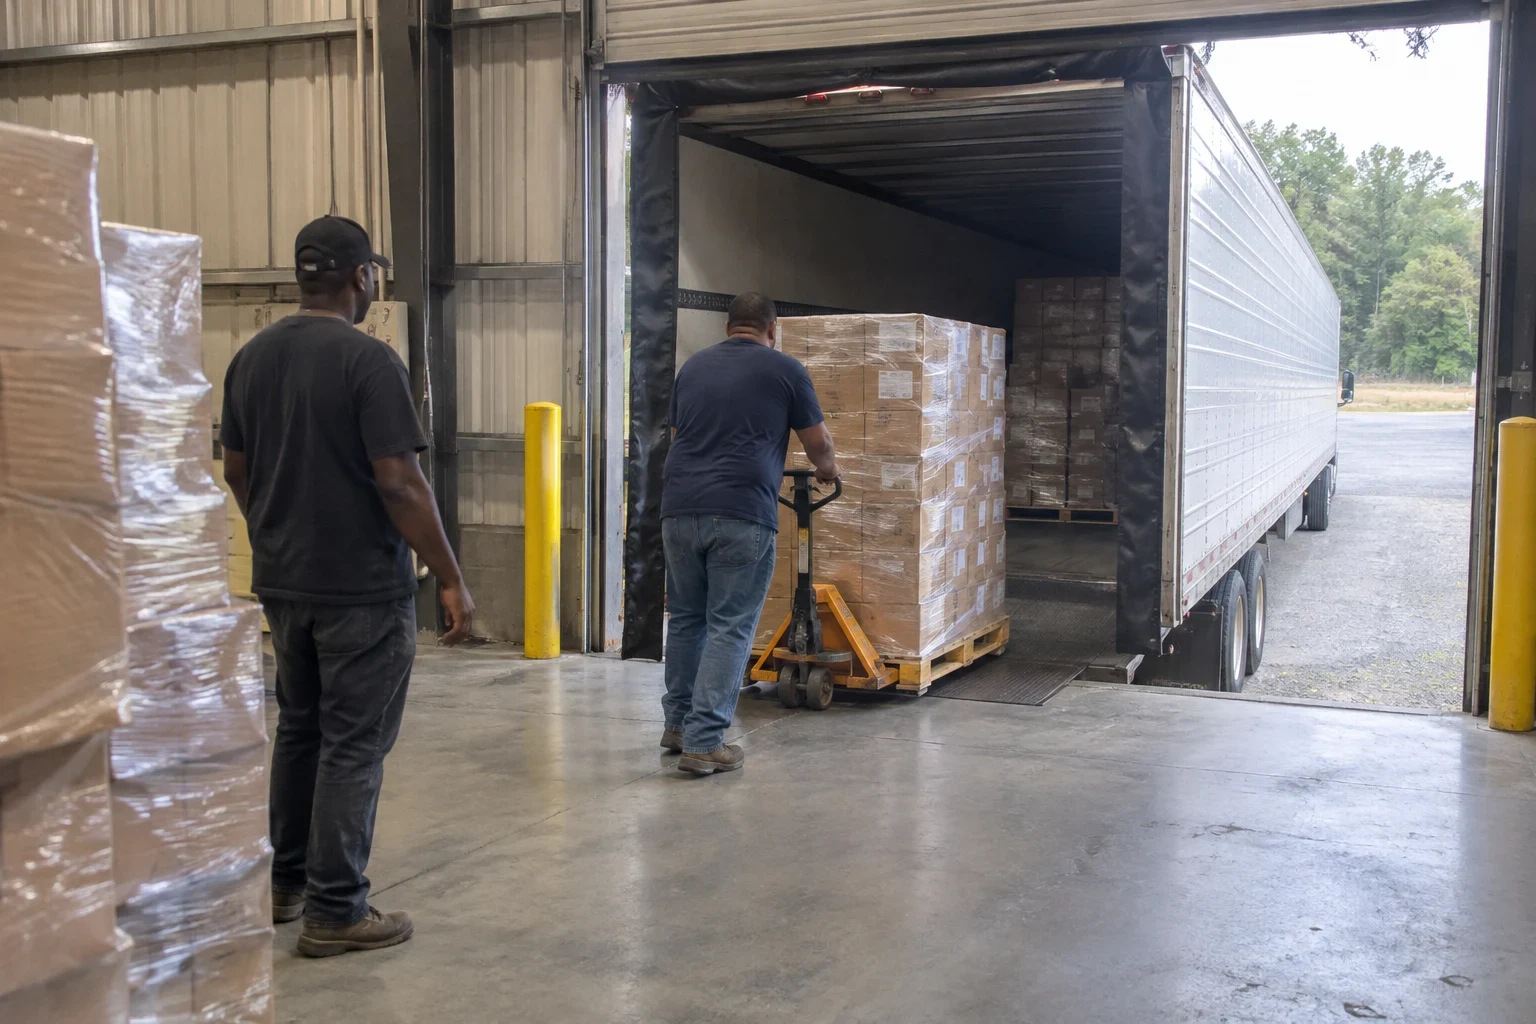
What cargo coverage pays for, and what it doesn't
Motor truck cargo insurance pays for the freight on your truck when it is lost or damaged while in your care. Think of a load that shifts and crushes, a fire, a rollover or a stolen trailer. It covers the shipper's goods, not your equipment. Your tractor and trailer fall under physical damage insurance.
Federal rules do not require cargo coverage for most general freight carriers, but nearly every broker and shipper will. Their contracts set the limit, sometimes the deductible, and they want a certificate of insurance on file before you are dispatched. We read those requirements with you so the policy matches what is being asked, not a guess.
Most problems we see come from the fine print: a commodity that is excluded, theft from an unattended truck, or reefer breakdown left off the policy. We go through those lines with you at our Fairburn office or by phone and video.
What we set up on your cargo policy
- 01
Limits that match your contracts
We look at the limits your brokers and shippers list and size the policy to meet them. If one customer asks for more than the rest, we talk through whether to raise the policy or handle that load separately.
- 02
A commodity review
You tell us what you haul. Some freight, like electronics, alcohol, tobacco or certain metals, can be excluded or priced differently, and we tell you plainly which of your loads are covered.
- 03
Reefer breakdown coverage
If you run refrigerated loads, spoilage from a unit failure is often a separate option. We add it when you need it and explain what the policy expects from your maintenance records.
- 04
Theft and unattended vehicle terms
Many cargo policies limit theft claims when the truck is left unattended or parked in an unsecured lot. We show you the exact wording so you know where and how you can stop.
- 05
Certificates for brokers and shippers
When you sign on with a new broker, we issue a certificate of insurance naming them as certificate holder, with the cargo limit shown the way their paperwork requires.
Questions about Motor Truck Cargo Insurance?
Call(770) 766-5839Signs it's time to look at your cargo coverage
A broker asked for a certificate
Load boards and brokers will not dispatch you without proof of cargo coverage. If you do not have a policy yet, that is the first thing to fix.
You're leaving a lease to run your own authority
The carrier you were leased to carried the cargo policy. Once you operate under your own MC authority, that coverage no longer follows you.
Your freight has changed
Switching from dry van to flatbed steel, or picking up food loads, can bring new exclusions. A policy written for your old freight may not respond to the new one.
Load values are creeping up
If some of your loads are now worth more than your limit, the difference could come out of your pocket after a claim.
You aren't sure what's excluded
If you have never read the exclusions page, or a past claim was denied, it is worth a second look before the next loss.
How getting cargo coverage works with us
- 1
Tell us about your freight
We start with a phone call, a video meeting or a visit to our office. We ask what you haul, your typical load values, your lanes, and your DOT number and MC authority details.
- 2
We check your contracts
Send us the insurance section of your broker or shipper agreements. We note the required limits, deductibles and any wording they want on the certificate.
- 3
Walk through the quote line by line
We explain the limit, deductible, commodity list and exclusions in plain language. You see what each option changes in the premium before you decide.
- 4
Coverage starts and certificates go out
Once you choose a policy and it is bound, we send certificates to the brokers you work with. When you add a new one later, you call us and we issue another.
What moves the price of cargo coverage
Cargo premiums are built from the risk of the freight itself and the way your operation runs. We cannot quote a number without your details, but we can tell you which choices raise or lower it. You will see each factor on your quote.
- What you haul
- High-value or theft-prone commodities cost more to cover than general dry freight. Refrigerated loads add the cost of reefer breakdown coverage.
- Limit and deductible
- A higher limit raises the premium. A higher deductible lowers it, as long as your contracts allow it.
- Experience and claims history
- Time under your authority, driver records and past cargo claims all weigh into pricing. Newer authorities usually pay more at first.
- Lanes and radius
- Where you run and how far from your base affects exposure. Long-haul routes with overnight parking are priced differently than short regional runs.
Cargo insurance questions we hear often
Is motor truck cargo insurance required by law?
For most general freight carriers, the federal government does not require it. In practice, brokers and shippers almost always do, and they set the limit in their contracts. Without it, you will have a hard time getting loads.
Does cargo insurance cover my truck or trailer?
No. Cargo coverage is for the freight you are carrying. Damage to your own tractor or trailer is covered by physical damage insurance, which we can quote alongside your cargo policy.
What happens if a load is worth more than my limit?
The policy pays up to its limit, and the shipper may come to you for the rest. If you take an occasional high-value load, call us before you accept it so we can look at raising the limit.
I'm leased onto a carrier. Do I need my own cargo policy?
Usually the carrier you are leased to provides cargo coverage, but check your lease agreement. If you plan to get your own authority, you will need your own policy before you haul under it.
Does the policy cover theft from a parked truck?
It depends on the wording. Some policies limit or exclude theft when the truck is unattended or not in a secured location. We show you that section during your quote so there are no surprises.
Get your cargo coverage matched to your next contract
Have your broker agreements and a list of what you haul handy. We will walk through the limits and exclusions with you and get your quote by phone.