ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Fairburn, GA
Short hauls, heavy loads and rough job sites call for coverage built around that work. We set up dump truck and construction truck policies, line up your filings, and make sure your certificate of insurance says what the contractor needs before you roll through the gate.
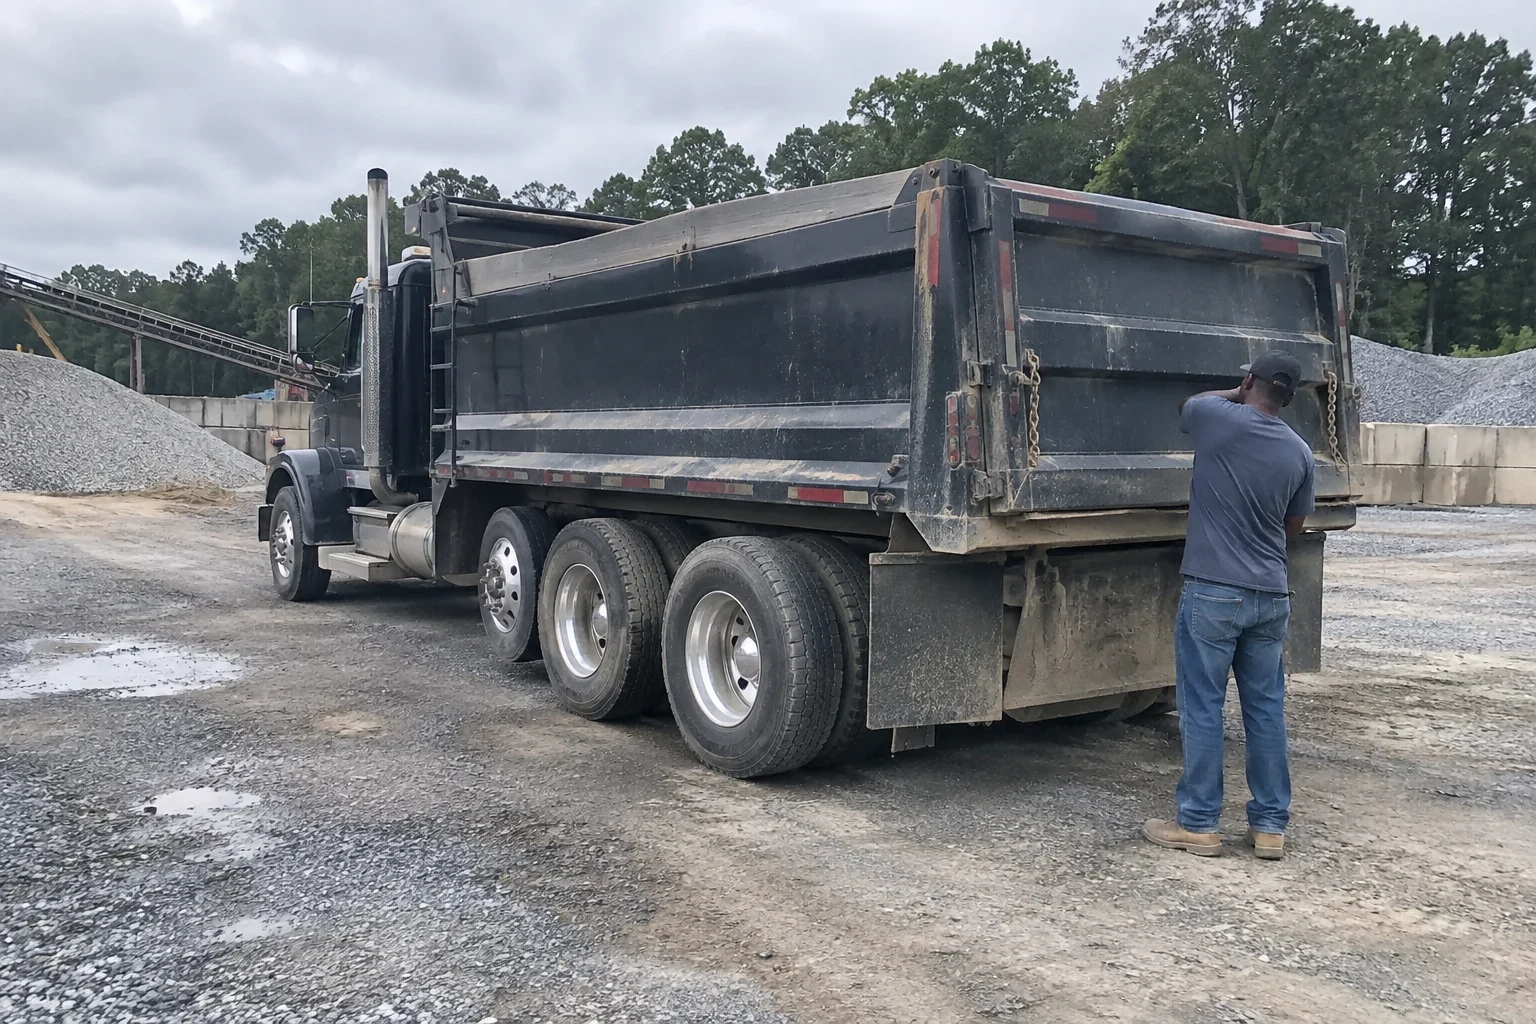
Coverage that fits how construction trucks actually work
Dump trucks and construction trucks don't run like over-the-road rigs. They make short, repeated trips, back onto soft and uneven ground, carry gravel, dirt or demolition debris, and park beside other contractors' equipment all day. A policy written for a highway tractor can leave gaps here, and a general contractor will notice them before you do.
We work with single-truck owner-operators and small construction fleets, and we explain each requirement in plain terms: which filings your operation needs, what limits a contract is asking for, and what a certificate has to show. If you haul for hire or cross state lines, your federal filings and DOT number have to match the policy exactly. If you only run inside Georgia, state requirements come into play instead. We figure out which applies to you before anything gets quoted.
What your dump truck policy can include
Primary auto liability sized to your contracts
This covers injury and property damage you cause to others while operating your trucks. We match the limit to what your filings and contracts call for, not just the legal floor. Our Primary Auto Liability Insurance page goes deeper on how limits work.
Physical damage for the chassis and the dump body
Collision and comprehensive coverage for the truck itself, including the dump body, hoist and tailgate. Those upfits are expensive to replace, so we make sure the stated value reflects the whole unit, not just the cab and frame.
Filings under the right name and number
When your operation needs a federal or state insurance filing, we file it under your exact legal name and DOT number. A small mismatch can hold up your authority, so we check it twice.
Certificates of insurance for each job
General contractors, quarries and public agencies often want their own certificate, sometimes with wording that names them on your policy or a waiver of subrogation. We prepare each one and compare it against the contract's requirements so it isn't sent back.
Non-trucking liability for leased-on haulers
If you're leased to a construction carrier, their policy may only cover you while you're under dispatch. We look at whether you need non-trucking liability for the rest of the time.
Signs it's time to review your construction truck coverage
- A contractor rejected your certificate
- Usually the limits are too low or the endorsement wording is missing. It's fixable, but it needs to be fixed on the policy, not just on paper.
- You added a truck or a driver
- Every unit and every driver has to be listed correctly. An unlisted driver on a job site is the kind of gap that turns a small claim into a large one.
- Your truck got a new body or upfit
- A new dump bed or hoist raises the value of the truck. If your physical damage coverage still shows the old number, a total loss won't pay what it costs to replace.
- You're moving into for-hire or out-of-state work
- Hauling for other companies or crossing into Alabama or beyond can trigger new filings. Better to set them up before the first load than after a roadside inspection.
- Your renewal jumped with no explanation
- You deserve to know what changed. We walk through the premium line by line and look for honest ways to bring it down.
How we set up your coverage
- 1
A call about your operation
We ask what you haul, how far, how many trucks and drivers you run, and who you work for. It takes one conversation by phone, by video or at our office.
- 2
Sorting out the requirements
We confirm your DOT number status, any filings you need, and the limits and wording your contracts require. If something is missing or mismatched, we tell you plainly.
- 3
Quotes explained in plain language
We bring back options and explain what each one covers, what it leaves out, and why the premiums differ. You choose with the full picture in front of you.
- 4
Binding, filings and certificates
Once you decide, we bind the coverage, take care of the filings and prepare the certificates your jobs call for. When you add a truck or start a new contract later, one phone call updates it.
What moves the price of dump truck insurance
Construction trucks are priced on the work they do and the risk that comes with it. Two trucks that look alike on paper can carry very different premiums. Here is what carriers weigh most.
- What you haul and where
- Sand and gravel to nearby sites rates differently than demolition debris or long runs between counties. Radius and material both count.
- Truck value and equipment
- Newer trucks and costly dump bodies raise the physical damage portion of the premium.
- Driver records and experience
- Clean motor vehicle records and years behind the wheel of heavy equipment make a real difference. Recent violations or inexperienced drivers push rates up.
- Limits your contracts require
- Higher liability limits cost more. Some public and commercial jobs require them, so we match the limit to the work you actually bid on.
- Time in business and claims history
- A newer operation or a recent loss will affect pricing. If you're just starting out, our New Authority Truck Insurance page covers what to expect.
Dump truck and construction truck insurance questions
- Do I need a DOT number if my dump truck only runs in Georgia?
- It depends on the truck's weight and whether you haul for hire. Many dump trucks are heavy enough that Georgia expects a USDOT number even for in-state work, and for-hire haulers have state insurance filings as well. We check your setup on the call and tell you which rules apply before we quote.
- Why does the contractor want more coverage than the law requires?
- Legal minimums protect the public on the road. Contractors set their own requirements to protect their projects, so their limits and wording are often higher. We go through the contract's insurance section with you and set up a policy that meets both.
- Is my dump body covered under physical damage?
- It can be, as long as it's included in the stated value of the truck. Bodies and hoists are often left out or undervalued when a truck first goes on a policy. We list the full unit so a claim pays what it should.
- I'm leased onto a construction carrier. What do I still need?
- Their policy usually provides primary liability while you're working under their dispatch. You may still need physical damage on your own truck and non-trucking liability for the time you're off dispatch. We look at your lease agreement and tell you where the gaps are.
- How do I get a certificate for a new job?
- Call us and read us the contractor's insurance requirements, or bring the contract to our office. We check that your policy meets them, adjust it if needed, and prepare the certificate with the right holder and wording.
Ready to get your trucks set up correctly
Tell us about your trucks, your drivers and the jobs you're bidding on. We'll explain your filings and coverage options and get your quote by phone.